
Back to Budgeting Basics: Spend Less on What Matters Less
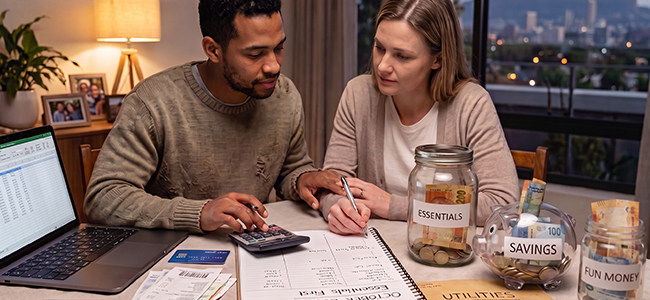
“A budget is telling your money where to go instead of wondering where it went.” (Dave Ramsey, author of The Total Money Makeover)
With living costs rising, many households are already looking more closely at their expenses. The temptation is to tackle the biggest debit orders first. A better starting point may be to ask: “Is my money still going where I actually want it to go?”
The spending you’ve stopped seeing
Unnecessary spending is often remarkably ordinary.
Subscriptions renew. A gym membership hangs around long after the enthusiasm for going to the gym has disappeared. Data packages, cloud storage, bank charges, and memberships continue in the background, largely because none of them seems significant enough on its own to worry about.
Go through three months of bank and credit-card statements and you may be surprised by what you find. It isn’t necessarily one extravagant purchase that makes the difference, but the combined cost of things you hardly notice paying for.
If that adds up to R1 500 per month, it amounts to R18 000 over a year. Suddenly the numbers become more interesting. That money could go towards an emergency fund, an investment, a holiday or paying down expensive debt.
Larger discretionary purchases deserve some thought too. There is nothing wrong with an expensive car, a designer handbag or a good restaurant if you can afford it and it genuinely matters to you. The question is whether you still value what you’re paying for, or whether your income, peer group or professional status has gradually changed your idea of what is “normal”.
Don’t begin with the important stuff
When household finances are under pressure, large monthly debit orders are often the first to come under scrutiny. Life and disability cover, medical scheme contributions, and voluntary retirement savings can look particularly expensive when added to a collection of smaller discretionary costs.
They are probably doing far more important jobs.
Before cutting insurance, go back to the reason you took it out and ask whether that risk still exists. Find out what you would lose before changing medical cover. If you are considering reducing voluntary retirement contributions, look at the effect on the retirement plan rather than simply the saving on next month’s debit order.
Of course, none of these costs is sacred. Circumstances change, products become inappropriate and financial plans need to be reviewed. The important distinction is between removing an expense you no longer need and giving up something valuable just to get some short-term breathing room.
What is your money keeping you from doing?
Picture a nurse in her fifties. She earns a decent salary, has always been fairly careful with money and would love to spend more time in Kruger. Yet the money for those trips never seems to be there.
Eventually, she goes through a few months of bank statements. There is no lavish purchase to blame. Over the years, her lifestyle has simply collected expenses. Some are useful, some have become habits and others she barely cares about anymore.
She leaves her medical scheme, insurance and retirement savings alone and starts trimming elsewhere. The money she saves goes into a travel account. Nothing dramatic happens to her day-to-day life, except that the wildlife trips she kept putting off start becoming affordable.
When extra money doesn’t feel like extra money
Budgets are not only for times when money is tight. They can be surprisingly revealing when income has been rising for years.
Spending has a habit of catching up with you. The occasional treat becomes routine; the car gets upgraded and expenses that once felt indulgent gradually become part of everyday life. A person can be earning considerably more than they did five or ten years ago without feeling much more financially secure.
Enjoying the rewards of earning well isn’t the problem. It becomes a problem when spending rises almost unnoticed and saving or investing is repeatedly postponed until the next increase.
This is also where a spending review becomes useful. Your financial planner needs to know what your lifestyle actually costs, not what you think it costs. That number influences how much cash you need in reserve, how much you can realistically invest and, eventually, how much income your capital may need to provide in retirement.
Pay less for what matters less
There is no right amount to spend on restaurants, holidays, cars or entertainment. One person’s extravagance may be another person’s great pleasure.
Nor should a budget strip all the enjoyment out of today in the interests of a distant future. But it is worth finding out whether today’s lifestyle is absorbing money that could give you more choices later.
The bottom line
Look at the expenses that have become habits. Keep the financial commitments that still have an important job to do. And when you find money being spent on something you no longer particularly value, give it another job.
A budget doesn’t just tell you where your money has been going. It also begs the question: “Where would you rather it went?”
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
